Revolut is positioning itself for a future beyond digital banking, with its chief executive describing ambitions to build a broader technology company around financial services, data and artificial intelligence. Reuters reported on October 9 that CEO Nik Storonsky spoke about the firm’s plans at a technology forum in Turin. Revolut, one of Europe’s most highly valued private technology businesses, has grown rapidly and is pursuing wider international reach. The ambition raises a business question: can a company known for financial apps extend into adjacent technology markets while keeping the trust and controls required for handling customers’ money?
From financial app to broader platform
Digital financial services companies often begin with a focused product, such as payments, foreign exchange or account management, then expand into savings, cards, credit, merchant services and other products. Each addition can make the platform more useful to customers and give the company more opportunities to earn revenue. But a larger product suite can also increase operational complexity and the number of risks that have to be managed.
Revolut’s stated ambition to expand beyond banking reflects a wider trend among technology businesses seeking to build ecosystems rather than single-purpose products. The success of that strategy depends on whether customers see genuine value in new features, whether the company can deliver reliable service across jurisdictions and whether management can invest without losing focus on its core business.
Transaction data and AI opportunities
Reuters reported that Revolut handles tens of millions of transactions daily and is exploring the use of proprietary AI models. Transaction data can help financial firms detect unusual activity, improve customer support, forecast demand and personalise tools. Such applications may make routine services quicker and help teams flag suspicious patterns for further review.
However, using financial data for AI requires careful governance. Customer information must be handled according to applicable law and privacy commitments, and model outputs need testing for accuracy, bias and unintended consequences. An AI system that wrongly flags a legitimate payment or misses suspicious behaviour can harm customers and create regulatory problems. Human oversight and clear paths to challenge a decision remain important for high-impact financial services.
Regulatory trust is part of the product
Financial technology firms compete on convenience, pricing and user experience, but customers also depend on safe handling of accounts and payments. Reuters noted that Revolut has faced regulatory challenges, including a fine imposed by Lithuania’s central bank in 2025 relating to transaction-monitoring deficiencies, as well as a reported 2026 data incident. These episodes underline why rapid expansion needs to be matched by strong compliance, data security and incident response.
Such incidents should be understood precisely. A regulatory fine or security incident is not automatically evidence that customer funds have been lost or that a company’s entire service is unsafe. At the same time, assurances from a company do not remove the need for independent oversight. Customers and investors should look at the nature of an incident, corrective steps, regulator findings and whether controls improve afterward.
International growth creates opportunities and obligations
Entering new markets can bring access to larger customer bases and allow a company to spread product development costs across more users. It also introduces different licensing requirements, consumer-protection regimes, privacy rules and expectations about customer support. A product that works well in one jurisdiction may need significant changes before it can be offered elsewhere.
Banking licences and regulatory approvals take time, and expansion requires investment in local compliance teams, risk controls and technology. Customers may benefit from more choice, but growth should not be measured only by the number of markets or products launched. Reliability, transparent fees and effective customer service are essential measures of long-term quality.
Competition with established technology companies
Revolut’s goal of becoming a broader tech company places it in a competitive environment where large platforms already control user relationships, infrastructure and significant research budgets. Financial firms have specific strengths, including deep knowledge of payment flows and regulated operations. To compete in adjacent markets, they need to identify where those strengths create a real advantage rather than simply copying popular technology features.
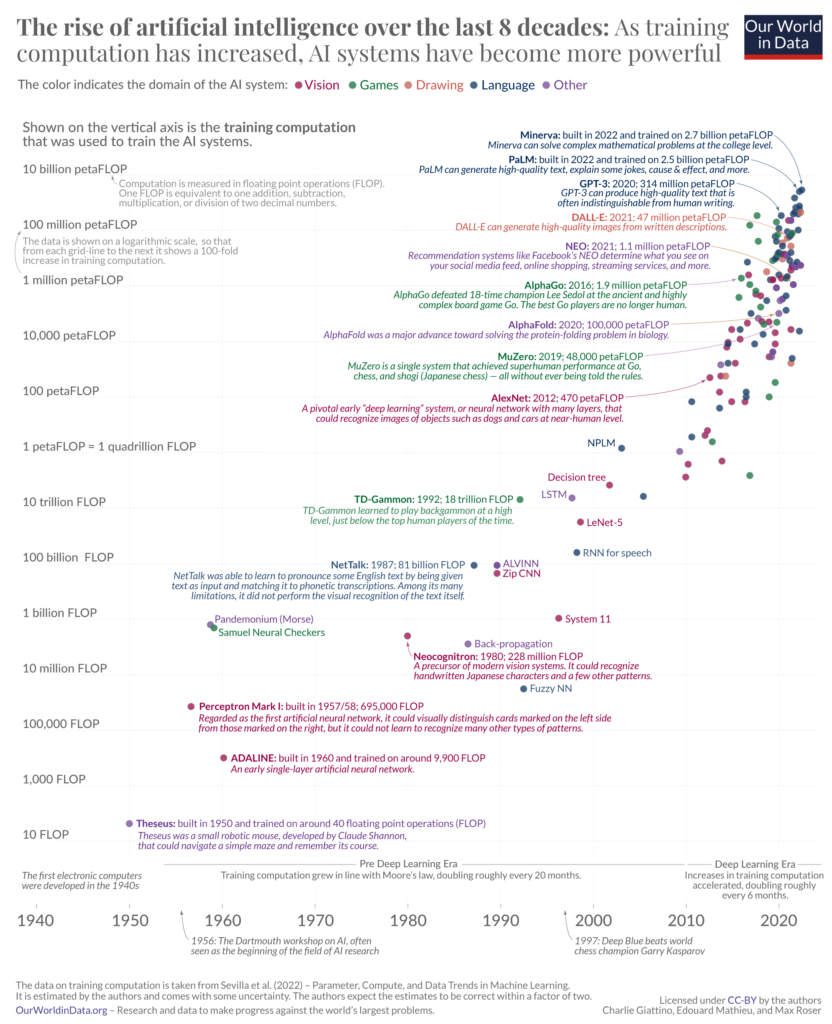
AI may help lower service costs or improve fraud detection, but it can also require expensive computing, specialised talent and continuous monitoring. The return on such investment depends on actual user adoption and measurable improvement. It is not enough to announce an AI roadmap; the company must show that it helps customers, increases reliability or supports sustainable revenue.
What customers and investors should watch
Customers can assess a financial platform by examining security settings, fee disclosures, support options, account protections and the clarity of its terms. They should use strong authentication and verify communications that ask for account access. Businesses considering the platform should also review settlement processes, service availability and how disputes are handled.
Investors will focus on revenue diversification, customer activity, profitability, compliance costs and the quality of risk management. Rapid growth can be valuable, but if it comes with weak controls or expensive expansion, the long-term economics may be less attractive. Clear reporting will help determine whether the company’s wider ambition is translating into durable business performance.
The next stage of fintech
The boundary between finance and technology continues to blur, with digital platforms combining payments, analytics, automation and customer services. Revolut’s ambition is one example of how fintech companies are trying to broaden their role. The opportunity is real, but success will require more than a larger menu of services: the platform must earn trust, demonstrate practical value and remain compliant as it grows.
For now, Revolut’s plans signal a strategic direction rather than a guarantee that it will become a technology giant on the scale of the largest global platforms. The coming years will show whether its data, AI work and international reach can deliver sustainable growth while maintaining the controls expected of a financial-services business.
Source: Reuters: Revolut aims to become global tech company beyond banking, CEO says.
All rights belong to their respective owners. This article contains references and insights based on publicly available information and sources. We do not claim ownership over any third-party content mentioned.